In our exclusive Design Fiction series for France’s CB News, we dive into the future through imaginative storytelling: short, thought-provoking pieces that explore what’s next for industries like fashion, tourism, banking, and more. Inspired by real signals shaping our world today, each article examines the possibilities ahead and unpacks what they mean for brands, communication, and strategy.
dentsu X imagines tomorrow, today.
The aim of this Design Fiction exercise is to analyze how our society's weak signals could change if they were to become the norm in twenty or thirty years. This exercise is not intended to predict the future, but rather to understand how brands could adapt to, or even play a role in, these possible transformations.
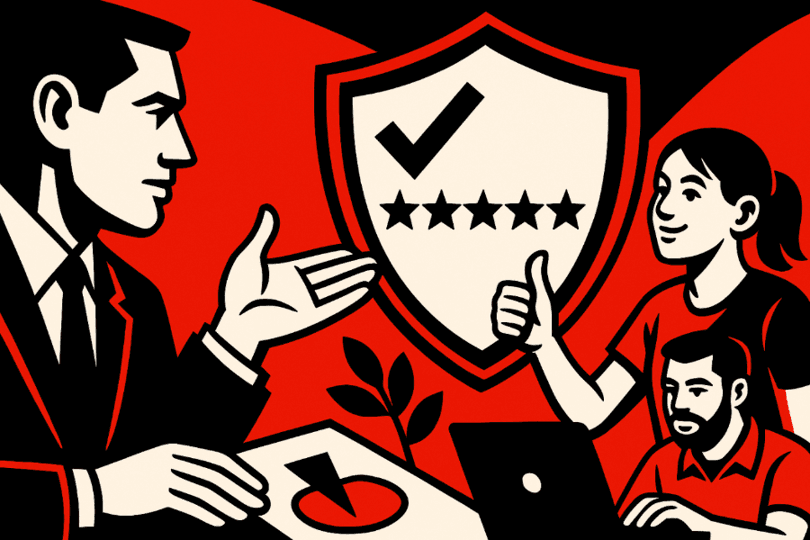
In this fictional scenario, Ethics, environmental impact, employee well-being, or tax transparency are now integrated into a reputation score. Named ReputEco, this score conditions access to professional financing.
This banking revolution, born in the rubble of a global scandal, has reshaped B2B finance. Between massive boycotts, drastic regulations, and service innovation, companies no longer fight solely to sell, they must prove they deserve trust. Here is the story of a systemic transformation where banks, entrepreneurs, and citizens rewrite the rules of the game together.
What if, tomorrow, obtaining a loan required as much proof of impact as financial guarantees? What if banking services became the guardians of economic ethics? What if a company's reputation score was worth more than its turnover?
Dateline:: 2042, France
Crisis of trust and the birth of ethical credit
In the early 2040s, distrust towards brands reached a peak: accusations of greenwashing, dubious social practices, and citizen boycotts amplified by social networks.
In this context, Joris, a young textile entrepreneur, sees his brand NATUROX collapse. Constrained by the market, he chooses, like many at the time, the path of the lesser evil: buying a label. A fake one. The supplier? LabelForge, a company based in Asia, champion of express certification, without audit, without control.
"We have no choice," Clémence, his marketing director, had said. "Everyone is doing it. If we don't, we sink."
Meanwhile, in the corridors of a renowned bank, Djeneba, a data scientist, cross-references data, digs through flows, and discovers the extent of the cheating. The highest-rated companies are also the most toxic. LabelForge comes up everywhere. She alerts, publishes, then co-founds Vigil-Eco, a citizen observatory of ethical practices.
In 2055, massive boycotts hit major retail chains. Consumers demand transparency, organize themselves, and markets plummet. The banks, blinded, are ostracized.
Faced with this crisis of trust, the State and international institutions establish in 2056 the ReputEco score, the new standard for ethical B2B credit integrating economic, social, and environmental criteria. An independent International Committee for Financial Reputation (CIRF) oversees the integrity of the system by evaluating companies and banks. From now on, only actors displaying a high score access preferential rates and certain markets, while non-compliant companies see their financing limited. Every two years, a mandatory audit allows for the review or revocation of loans to companies that no longer respect the standards, thereby strengthening the natural selection of the most responsible actors.
A new B2B banking landscape
In this new landscape, banks and B2B services adapt together: specialized platforms support all companies, in particular artisans or very small businesses (VSEs) that often do not have the internal means to build their ReputEco score, by centralizing CSR data, audits, and progress plans. This file, transmitted to partner banks, allows the offer and the credit rate to be adjusted according to the level achieved, while a market of support solutions facilitates access for the smallest structures.
These new banking solutions create a virtuous dynamic. On the one hand, B2B services support entrepreneurs in the continuous improvement of their practices. On the other hand, they reassure financial partners by guaranteeing scoring based on traceable and updated data.
In this changing ecosystem, B2B banking services like Quirra position themselves as key partners. In a few clicks, a restaurateur, a freelance graphic designer, or a local cooperative can access a negotiated loan, valuing their ethical efforts.
When humans take back control: from punitive to restorative finance
But beyond the tools, it is the men and women who embody this new finance. Among them, some have switched sides, renouncing the logic of yield to embrace that of restoration. Jacques is one of them. He has put away his suits. He used to be a banker. He lent unscrupulously, as long as the ROI was good. Until the LabelForge affair. Now, he listens, he helps, and he measures the truth as a CIRF advisor.
One morning in June, he visits a small textile worker cooperative (Scop) in the Vaucluse, whose ReputEco file was prepared via the Quirra platform. The company wishes to obtain a loan to expand its workshop, and Quirra has already generated a pre-diagnosis, structured the CSR data, aggregated the impact evidence, and simulated several financing scenarios. Jacques arrives to validate in the field what the interface has consolidated upstream. Upon arrival, he recognizes Joris, now a worker and co-manager of the Scop. Formerly at the head of NATUROX, he is today a player in a mission-driven company. "I cheated to survive. But now, I want to grow without deceiving." Jacques nods. He talks with the employees, consults the production registers, navigates the Quirra dashboard displayed in the common room. The indicators align with the declared commitments: low turnover, closed-loop recycling, and shared governance.
A few days later, the regional bank grants the Scop a loan at a preferential rate. The ReputEco score, validated: 87/100. Level A.
Transmission and the new generation: training for responsible finance
A few months later, Jacques joins Djeneba to co-build a training module on "moral credit" in a business school. Jacques and Djeneba pass on to students the keys to a finance aligned with ethics and impact. This "moral credit" module is only the first step of a complete support cycle: mentoring, auditing, transparency, and finally, participation in a grand national pitch finale.
There, for example, one comes across Lina and Kamil, two former sociology and design students, now co-founders of Biotrail, an impact-driven food traceability start-up. Their project, born in the corridors of a campus, was selected by the ReputEco jury and now benefits from an advantageous microcredit for its launch. "This system doesn't judge us on our banking past, but on our societal project," they explain to the local press. Through them, a new generation proves that profitability and responsibility can coexist.
Towards a new grammar of trust
In 2060, companies no longer just ask: "Am I profitable?" They ask: "Am I virtuous and trustworthy?"
ReputEco has become a shared standard between B2B banking services and traditional banks. For the former, it is a platform for innovation, differentiation, and advice. For the latter, a filter of trust and mastered risk. Together, they create a new grammar of credit: based no longer solely on numbers, but on proof of impact.
For many, like Jacques, Joris, and Djeneba, it is more than a system: it is a second chance, a new way of living their profession, of weighing the economy differently, with coherence.
Originally published in CB News, July 15, 2025: "LabelGate, The New Ethics Bank Loan."